TL;DR: PIP claim denials in Florida often stem from late filing, lack of medical necessity, treatment gaps, or disputed causation. Insurers scrutinize every detail, from the 14-day treatment deadline to whether care relates directly to the accident. Understanding what triggers these disputes reveals where coverage stands on firm ground and where it begins to fracture.
A denial letter arrives after weeks of treatment bills and mounting anxiety. The accident happened. The injuries are real. Yet the insurer now claims no obligation to pay. The reasons cited feel technical, abstract, removed from the physical reality of pain and recovery. What triggers a PIP coverage dispute is not always a question of fraud or exaggeration. More often, it is the collision of statutory deadlines, medical documentation gaps, and insurer interpretation of what qualifies as reasonable and necessary care. The dispute does not announce itself at the accident scene. It surfaces later, when the claim file is reviewed and someone decides the coverage does not apply.
Florida’s no-fault system promises swift payment of medical expenses and lost wages regardless of who caused the crash. But that promise carries conditions. When those conditions are not met, or when an insurer believes they were not met, the claim enters contested territory. The question is no longer whether coverage exists in theory, but whether it applies to this specific treatment, this specific injury, this specific timeline.
The 14-Day Treatment Rule and Initial Treatment Gaps
Under Florida Statutes § 627.736, you must seek initial services and care within 14 days of a motor vehicle accident to be eligible for any Personal Injury Protection (PIP) medical benefits. If you miss this critical 14-day window, you forfeit your right to PIP medical coverage for that accident. This is not a soft guideline; it is a statutory gate that closes with precision, and insurers will deny a claim outright if the first treatment occurs on day 15.
Even if you comply with the 14-day rule, the amount of coverage available depends on your diagnosis. To access the full $10,000 in PIP medical benefits, a qualified provider, a physician, osteopathic physician, dentist, physician assistant, or advanced registered nurse practitioner, must determine that you have an “emergency medical condition” (EMC). Without that determination, your PIP medical benefits are limited to $2,500.
The rule exists to prevent delayed claims and speculative treatment. But it also penalizes those who wait to see if soreness resolves on its own, who lack transportation, or who do not immediately recognize the severity of their condition. Whiplash, soft tissue injuries, and even some herniated disc symptoms may not fully manifest in the first 48 hours. By the time pain becomes unbearable, the clock has already run. The insurer does not assess intent or reasonableness; only whether the calendar supports the claim.
Medical Necessity and the Independent Medical Examination
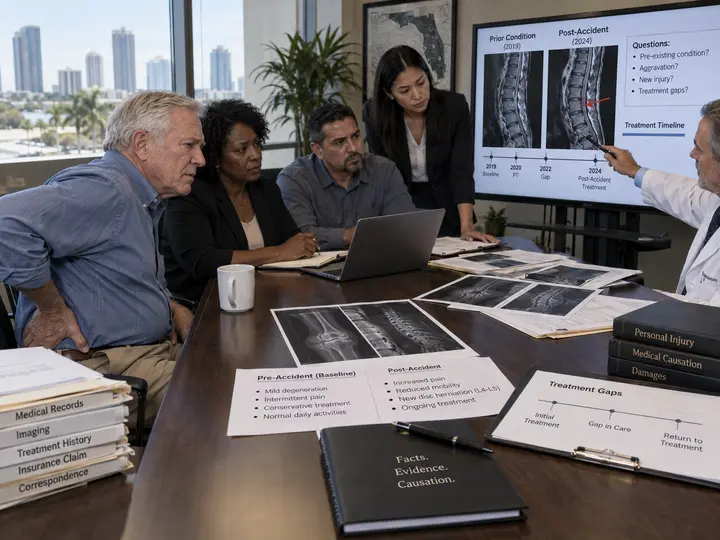
PIP coverage extends only to care that is “reasonable, related, and medically necessary.” Those three adjectives carry enormous weight. Insurers do not defer to the treating physician’s judgment. They retain the right to question every procedure, every scan, every therapy session. When doubt arises, the insurer may require the claimant to submit to a medical examination by a physician of the insurer’s choosing, commonly called an independent medical examination, or IME. The physician conducting that exam owes no allegiance to the claimant and often concludes that treatment has exceeded what the injury requires.
A herniated disc may justify an MRI and a course of physical therapy. But 12 weeks of chiropractic adjustment, multiple epidural injections, and ongoing pain management can trigger a necessity review. The IME doctor examines the file, not just the patient. Range of motion, diagnostic imaging, and prior medical history all factor into the analysis. If the IME report states that further treatment is unwarranted or that the current regimen exceeds standard protocols, the insurer may issue a partial or full denial of further benefits.
Claimants rarely know the examination is scheduled until the appointment notice arrives. The examination itself is brief, often 15 minutes or less. Yet the resulting report can sever coverage for thousands of dollars in pending and future care. Disputing an IME opinion requires competing medical evidence, which PIP claims do not always accommodate before benefits are cut off. The claimant is left paying out of pocket or halting treatment while the dispute plays out.
Common Triggers for Necessity Disputes
- Extended chiropractic treatment beyond six to eight weeks without objective improvement
- Repeated diagnostic imaging with no change in findings
- Pain management referrals when physical therapy has not been attempted
- Treatment for pre-existing conditions not aggravated by the accident
- Passive modalities, massage, ultrasound, heat, without active rehabilitation
None of these alone proves lack of necessity. But each raises a flag. Insurers look for patterns that suggest overutilization or treatment driven by billing rather than recovery. When the pattern emerges, the necessity challenge follows.
Causation Disputes and Pre-Existing Conditions
A claim can satisfy the 14-day rule and pass the necessity test yet still face denial on causation grounds. PIP covers injuries arising out of the ownership, maintenance, or use of a motor vehicle. If the insurer believes the condition existed before the crash, or arose from an intervening event, coverage does not apply. Causation disputes hinge on medical records, diagnostic imaging, and the claimant’s history. A degenerative disc visible on post-accident MRI becomes evidence of a pre-existing condition. The insurer argues the accident did not cause the herniation; it merely revealed what was already there.
Florida law recognizes aggravation of a pre-existing condition as compensable. But proving aggravation requires comparing baseline health to post-accident status. Without prior imaging or medical records documenting the condition before the crash, that comparison becomes speculative. The insurer denies on the grounds that the claimant has not met the burden of proving the accident worsened the underlying pathology.
Causation also fractures when treatment gaps appear. A claimant seen immediately after the accident, then not again for six weeks, invites questions about what happened during the interval. Did symptoms improve and then recur due to an unrelated event? Did the claimant engage in activity that caused new injury? The insurer does not need proof of an intervening cause; only enough ambiguity to question whether the current complaint ties back to the original collision. Understanding how Florida car accident claims are built helps clarify when causation becomes contested and what evidence bridges the gap.
Unreasonable or Excessive Billing Practices
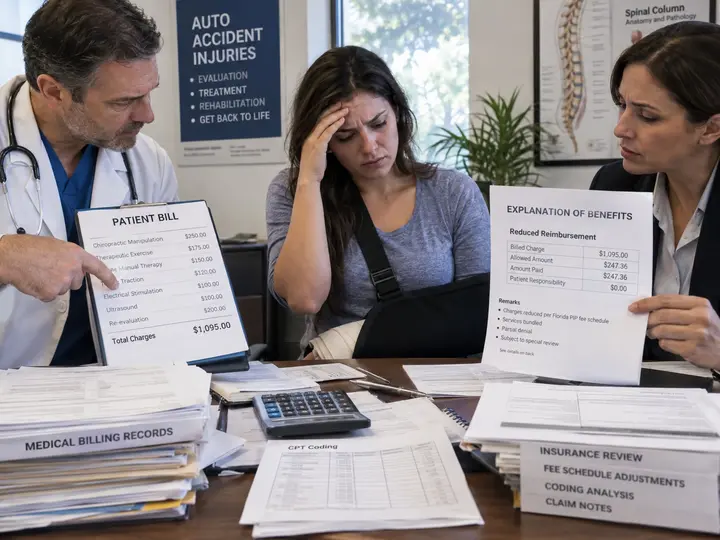
PIP reimburses 80 percent of reasonable medical expenses. “Reasonable” does not mean whatever the provider charges; it means what the insurer deems appropriate under the statutory fee schedule or usual-and-customary standards. A provider bills $500 for an examination. The insurer reduces payment based on Medicare-based fee schedules or a proprietary database. The claimant is caught between the provider’s expectation of full payment and the insurer’s reduced reimbursement.
Some disputes arise from billing codes. A provider submits separate codes for evaluation, adjustment, and modalities during a single visit. The insurer bundles them into one reimbursement, citing coding rules. Other disputes involve out-of-network providers whose charges exceed in-network rates. PIP does not require the claimant to use network providers, but reimbursement is still limited to reasonable amounts. The difference falls on the claimant or the provider, depending on the treatment agreement.
Excessive billing can also trigger a fraud investigation. When charges appear inflated or when the frequency of visits exceeds clinical norms, insurers flag the claim for special review. That review delays payment and often results in partial denial. The claimant, who may have had no knowledge of the provider’s billing practices, faces reduced benefits and potential balance billing.
Documentation Failures and Incomplete Claim Submissions
A technically valid claim can be denied for administrative reasons. Missing intake forms, unsigned authorizations, incomplete accident reports, any gap in the claim file gives the insurer grounds to withhold payment. Florida Statutes § 627.736 conditions payment on the insurer’s receipt of written notice and statements of charges, and it sets outside deadlines for submitting bills after treatment is rendered. Records sent late or in incomplete form can result in denial for untimely or unsupported submission.
Providers often bear responsibility for documentation. They must submit itemized bills, treatment notes, and diagnostic reports. When a provider’s billing department sends incomplete records or fails to include the accident narrative, the insurer denies for lack of proof. The claimant, unaware of the administrative breakdown, discovers the denial only when a bill arrives marked “patient responsibility.”
Coordination of benefits adds another layer. Depending on the policy and any elected deductible or coverage-priority provisions, PIP may interact with health insurance, Medicare, or Medicaid, and the insurer may require an explanation of benefits before processing the claim. Missing EOBs or coordination forms result in denials that appear to the claimant as outright refusals to pay, when in fact the issue is procedural. For broader context on how bodily injury claims differ from PIP, consider the distinct proof requirements and timelines each demands.
Coverage disputes do not always signal bad faith, but they frequently reveal where procedural compliance, medical documentation, and insurer scrutiny intersect. The triggers are statutory, clinical, and administrative. They operate independently and in combination. A claim denied for one reason may also fail on another. What appears as a single denial letter is often the product of multiple deficiencies, each sufficient on its own to limit or extinguish benefits. Recognizing the triggers before the denial arrives is the difference between navigating the claim and colliding with it.
Closing Remarks
When a PIP denial arrives citing missed deadlines, disputed medical necessity, or questioned causation, the path forward can feel uncertain and overwhelming. You are not just dealing with an insurance claim; you are dealing with your health and your financial stability. You do not have to face this alone. At CDB Injury Law, Chris Debari has spent his career standing beside injured people across Florida, helping them cut through the runaround and reclaim a sense of control. Let us talk about your recovery.
Frequently Asked Questions
What happens if treatment begins on the 15th day after the accident?
If your initial services and care occur on the 15th day or later, Florida Statutes § 627.736 generally bars PIP medical benefits for that accident, and the insurer will deny the claim on eligibility grounds. The difference between the $2,500 limit and the full $10,000 limit only comes into play when treatment begins within the 14-day window; it turns on whether a qualified provider determines you have an emergency medical condition. Because the facts around when care actually began are sometimes disputed, it is worth having the denial reviewed rather than assuming the door is closed.
Can an insurer deny a claim based solely on an IME report?
An IME report provides grounds for questioning medical necessity, but it is not automatically dispositive. Under Florida Statutes § 627.736, an insurer may withdraw payment for future treatment only after a physician licensed under the same chapter as the treating provider examines the insured and reports that the treatment is not reasonable, related, or necessary. If the IME conflicts with the treating physician’s opinion, the dispute often requires additional review, peer evaluation, or litigation. A denial resting on a cursory examination that ignores the treating provider’s clinical notes may itself become the subject of the dispute.
Does a pre-existing condition always disqualify PIP coverage?
No. PIP covers aggravation or exacerbation of a pre-existing condition when the accident worsens the baseline condition. The challenge is proving the aggravation. Without prior medical records showing the state of the condition before the crash, establishing a causal link becomes difficult. Insurers often deny claims involving degenerative disc disease, prior surgeries, or chronic pain by arguing the accident caused no new injury. Overcoming that denial usually requires medical opinion evidence comparing pre-accident and post-accident imaging, functional capacity, and symptoms.
What recourse exists when a provider’s billing triggers a denial?
If the denial stems from excessive or improperly coded billing, the claimant can challenge the insurer’s fee determination or ask the provider to resubmit corrected billing. Disputes over reasonable charges often require review of usual-and-customary rates in the geographic area and specialty, measured against the statutory schedule the policy adopts. The claimant is not automatically liable for the balance, particularly if the provider agreed to accept PIP reimbursement as payment in full. When the billing dispute reflects systemic overcharging by the provider, the claimant may need independent legal advice to avoid being caught between the insurer and the provider.
How long does an insurer have to pay or deny a PIP claim?
Florida Statutes § 627.736 requires insurers to pay PIP benefits within 30 days after receiving written notice of a covered loss and the amount of it, subject to the insurer’s right to extend that period when it has reasonable proof of suspected fraud. Overdue payments bear simple interest at the rate established under Florida Statutes § 55.03, which the Chief Financial Officer sets quarterly, or the rate stated in the policy, whichever is greater. Persistent delays without a valid reason, such as repeated requests for duplicative documentation, can support a claim that the insurer is not handling the file in good faith. Tracking submission dates, follow-up correspondence, and payment history is essential when delays extend beyond the statutory period.
References
- Florida Statutes § 627.736 (Personal Injury Protection Benefits).
- Florida Statutes § 55.03 (Judgments; Rate of Interest).