TL;DR: Insurers investigating pre-existing conditions typically request medical records spanning three to ten years before the accident, pharmacy logs, employment files, prior claims history, and Social Security disability applications. These requests aim to quantify what portion of current complaints existed before the incident and what the accident genuinely caused. Understanding what records arrive and what they reveal shapes every settlement conversation that follows.
Medical bills arrive. Treatment begins. Then the carrier sends a records authorization form covering “all prior medical history.” The scope feels boundless because it often is. If you are staring at that form wondering how much of your life you are about to hand over, that unease is warranted. Insurers do not request pre-existing condition records to understand your health. They request them to reduce what they pay. The records themselves are neutral; the interpretation is strategic. What arrives in the adjuster’s file becomes the architecture of every coverage dispute, causation argument, and settlement calculation that follows. You do not have to navigate that alone.
Medical Records: How Far Back Carriers Reach
Standard medical authorization forms in Florida allow insurers to request records from any provider, for any condition, across a timeframe the carrier defines. Most adjusters begin with a three-year lookback. Complex cases (spinal injuries, joint replacements, psychological claims) often trigger requests reaching seven to ten years into the past. Carriers are not required to limit their search to conditions directly related to the current claim. A rotator cuff tear from a rear-end collision may prompt requests for cardiology notes, psychiatric treatment summaries, and records from an urgent care visit five years earlier for bronchitis.
The scope expands when initial records hint at prior complaints. A single mention of “chronic lower back discomfort” in a primary care note from four years ago becomes justification to request every imaging study, specialist consultation, and physical therapy intake form since that date. Adjusters cross-reference diagnosis codes across providers. ICD-10 codes appearing in multiple records, even for resolved or unrelated conditions, become data points in the carrier’s causation analysis.
Electronic health record systems have made retrospective searches faster and more exhaustive. Carriers now receive consolidated records from hospital networks spanning multiple facilities and years. A claimant treated at three different emergency rooms within the same health system may see all three visits summarized in a single transmission, each visit annotated with prior diagnoses, medication lists, and social history notes that predate the accident by years.
Pharmacy Records and Prescription Histories
Pharmacy benefit managers maintain centralized databases tracking every prescription filled, dosage change, and refill pattern. Insurers request these logs to establish medication timelines that either support or contradict current treatment narratives. A claimant now taking opioids for post-accident pain may face questions if records show similar prescriptions filled two years earlier. The prior prescription may have been for dental surgery, but the adjuster’s initial report will note “history of narcotic use” without context.
Carriers scrutinize gaps and overlaps. A muscle relaxant prescribed six months before the accident, then discontinued, then restarted immediately after the collision, suggests to an adjuster that the current injury re-aggravated a dormant condition. Adjusters compare dates prescribed, quantities dispensed, and refill compliance. A prescription written but never filled signals the prior condition may not have been significant. A prescription refilled monthly for years, then discontinued, then resumed post-accident, tells a different story.
Psychotropic medications attract particular scrutiny in claims involving non-economic damages. Antidepressants or anxiolytics prescribed before the accident are offered as evidence that emotional distress claimed now has pre-existing roots. Adjusters rarely volunteer the medical reality that medication for generalized anxiety differs materially from PTSD triggered by a collision.
Employment and Disability Files
Workers’ compensation claims, short-term disability applications, and FMLA records surface whenever insurers suspect prior injury. A claimant alleging a career-ending shoulder injury from a T-bone crash will face hard questions if employment records show a workers’ compensation claim for the same shoulder three years earlier. Even if that claim closed with no permanent restrictions, the file provides a baseline: imaging from the prior injury, range-of-motion measurements, and treating physician notes describing pre-accident function.
Social Security disability applications, whether approved or denied, generate detailed medical summaries. Applicants must document functional limitations across every aspect of daily living. Those statements, certified as true by the applicant, can be used as admissions when they conflict with current claims. A claimant who reported in a disability application that chronic pain prevented prolonged sitting, then later attributes that same limitation solely to the recent accident, hands the carrier impeachment material.
Attendance records, accommodation requests, and performance reviews add texture. Repeated requests for ergonomic adjustments, reduced hours, or modified duties suggest limitations existed before the collision. Supervisors’ notes describing physical struggles or frequent absences are used as evidence the accident did not create the impairment but revealed or worsened what was already there.
Prior Insurance Claims and Litigation History
Insurers search industry claims databases and state claims indexes for prior bodily injury claims. A claimant with two prior rear-end collision claims involving cervical strain now faces a “frequent claimant” flag that adjusters treat as presumptive evidence of exaggeration. The prior claims may have been legitimate, fully compensated, and unrelated to current injuries, but the pattern triggers skepticism. Adjusters assume each subsequent claim involves less new injury and more re-injury of a vulnerable area.
Litigation histories carry weight beyond their outcomes. A dismissed claim still appears in public records. An arbitration that ended in a defense award still shows the claimant pursued compensation before. Carriers interpret patterns: multiple claims within short timeframes, overlapping treatment for similar body parts, or repeated use of the same treating physicians. None of this proves fraud, and none of it changes who carries the legal burden of proof. In practice, though, it changes the tenor of settlement negotiations. The claimant is pressed to show, record by record, that each injury is distinct and accident-caused.
Medical malpractice claims create their own complications. A claimant who previously sued a surgeon over a spinal fusion now alleges new spinal injury from an accident. The carrier will request the entire malpractice file: expert reports, deposition testimony, surgical records, and imaging. The goal is to isolate which deficits the malpractice caused, which the accident caused, and which existed before either event. When overlapping causation clouds liability, settlement leverage shifts toward the party prepared to litigate causation with credible expert testimony.
What Adjusters Look for in the Records
Once records arrive, adjusters map prior complaints to current injuries. The analysis focuses on consistency, progression, and new versus chronic findings. Key data points include:
- Diagnosis codes appearing in multiple pre-accident records: Repeated ICD-10 codes for the same body region suggest chronic issues rather than acute trauma.
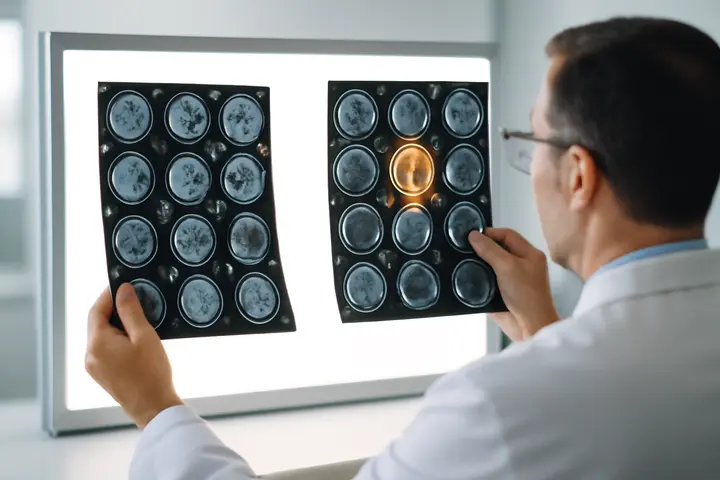
- Imaging comparisons: An MRI six months before the accident showing a bulging disc at L4-L5, followed by a post-accident MRI showing the same bulge unchanged, is argued as evidence the accident did not cause the disc finding.
- Symptom descriptions across time: A claimant reporting “daily headaches” in primary care notes from two years before the crash cannot easily claim headaches began post-accident.
- Treatment timelines and gaps: Chronic complaints treated intermittently, with long gaps between care, are used to suggest lower severity than current treatment intensity implies.
- Functional capacity assessments: Prior records showing limited range of motion, use of assistive devices, or work restrictions establish a pre-accident baseline against which current restrictions are measured.
Adjusters are trained to distinguish aggravation from causation. Florida law allows recovery for aggravation of a pre-existing condition, and Florida’s standard civil jury instruction on aggravation directs that damages be measured by the aggravation itself when the effects can be separated, not by the entire underlying condition. Where the aggravation cannot reasonably be separated from the pre-existing condition, the instruction permits recovery for the condition as a whole. Quantifying that difference requires detailed records. When prior imaging shows degenerative changes and post-accident imaging shows those same changes plus a new acute finding, the acute finding supports the claim. When imaging shows only the pre-existing degeneration, the carrier argues the accident caused nothing new.
Consider a hypothetical: A claimant suffers a torn meniscus in a side-impact collision. Prior records reveal arthroscopy on the same knee four years earlier for a different meniscal tear, which healed fully. The carrier requests operative reports, post-surgical imaging, and physical therapy discharge summaries. The records confirm complete recovery and return to normal activity. In that scenario, the new tear is far easier to present as a distinct injury. Had the prior tear never fully healed, and post-accident imaging showed only worsening of the original tear with no new acute damage, the carrier would argue the accident aggravated a chronic condition rather than causing a new one. Outcomes depend on the specific facts, the medical opinions offered, and the evidence presented.
How Records Shape Coverage and Causation Disputes
Pre-existing condition records feed two distinct defense strategies: coverage denials and causation disputes. Coverage denials assert the claimed injury or treatment falls outside policy terms, often through policy exclusions or through PIP exhaustion arguments where prior treatment consumed available benefits. Causation disputes accept that coverage applies but contest how much of the current condition the accident actually caused.
Causation apportionment is where most of these fights are resolved. When a carrier concedes that an accident aggravated a pre-existing condition, the settlement calculation attempts to isolate the incremental harm. If prior records show a claimant had a 40% range-of-motion restriction before the accident, and current evaluation shows 60% restriction, the carrier will value the claim around that 20-percentage-point difference rather than total disability. Offers are reduced accordingly, and treatment gaps or inconsistent care documentation amplify the reduction. This is separate from Florida’s comparative fault statute, which apportions damages based on each party’s share of fault, not based on medical causation.
The burden of proving causation rests with the claimant. When pre-existing records are extensive and current medical opinions equivocal, that burden becomes difficult to meet. A treating physician who opines that the accident “may have” aggravated a condition, or that symptoms are “consistent with” trauma, provides weaker causation evidence than one who states, to a reasonable degree of medical probability, that the accident caused new structural damage. Adjusters exploit hedged language. They interpret “may have” as “may not have” and reduce offers to reflect the ambiguity.
Discovery in litigation expands the record universe. Defense counsel subpoena records from providers identified in discovery, then depose treating physicians to ask whether each current complaint could stem from prior conditions. Cross-examination focuses on alternative causation theories: degenerative changes that would have progressed regardless of the accident, lifestyle factors contributing to pain, psychological stressors unrelated to the collision. Pre-existing records are the foundation for each alternative theory. Florida’s discovery rules do allow objections to requests that are overbroad or not relevant to the claims at issue, and the scope of what a carrier ultimately receives is not always what it first asks for.
The records themselves do not decide outcomes. Interpretation does. Two physicians reviewing identical pre-accident imaging may reach opposite conclusions about whether post-accident complaints represent new injury or chronic progression. The difference lies in how the records are framed, which comparisons are drawn, and whether the narrative centers on what changed or what stayed the same. Insurers begin building their narrative from the first authorization form they send. By the time settlement discussions begin, the carrier’s version of your medical history is already drafted, footnoted, and filed. You are entitled to have your own version told with the same care.
Closing Remarks
If a carrier has requested records spanning a decade, if prior imaging or prescriptions now dominate the adjuster’s evaluation, or if settlement offers reflect causation disputes rather than the injuries you actually sustained, the records have already reshaped your claim. Having a history does not make your injury less real. CDB Injury Law represents injured people navigating pre-existing condition disputes in Florida personal injury claims, building causation records that separate what the accident caused from what came before. You do not have to face this alone. Let us talk about your recovery.
Frequently Asked Questions
Can an insurance company request medical records unrelated to my injury?
Often, yes, if the authorization you signed permits it. Broad medical release forms allow carriers to request records from any provider for any condition within the specified timeframe. Adjusters routinely request records beyond the claimed injury to search for pre-existing conditions, prior treatments, or alternative causation factors. Authorizations can frequently be narrowed in scope, and in litigation a court can limit requests that are not relevant to the claim. Review any authorization carefully, ideally with counsel, before signing it.
What happens if I refuse to provide pre-existing condition records?
Refusing records the carrier reasonably requests can lead to delay, benefit suspension, or denial. Florida’s PIP statute and most bodily injury policies condition payment on reasonable cooperation with the investigation, which can include examinations and recorded statements. That said, a carrier’s request is not automatically reasonable simply because it is made. The better approach is usually to respond through counsel, who can object to overbroad demands while preserving your claim.
How do insurers use pharmacy records in injury claims?
Pharmacy records establish medication timelines that adjusters compare to claimed injury onset. Prescriptions for pain management, muscle relaxants, or psychotropic drugs filled before the accident are used to suggest prior symptoms. Adjusters examine dosage changes, refill patterns, and gaps in use to argue current complaints existed before the collision or that the accident merely resumed treatment for a chronic condition. Context (such as a short course of pain medication after dental surgery) is rarely supplied by the carrier and usually has to be documented by you.
Does a prior workers’ compensation claim affect my car accident settlement?
A prior workers’ compensation claim for the same body part gives the carrier baseline medical records, functional assessments, and any impairment ratings predating the accident. Adjusters use those records to argue the accident aggravated a pre-existing condition rather than causing a new one. Under Florida’s aggravation standard, damages are measured by the worsening where the effects can be separated, which carriers use to push settlement value down. Clear evidence of full recovery before the crash is often the strongest counterweight.
Can an insurer see records from a Social Security disability application?
Frequently, yes. Social Security disability files contain detailed functional assessments, treating physician statements, and your own descriptions of physical and mental limitations, and they are often obtained through authorizations or discovery in litigation. Statements describing chronic pain, mobility restrictions, or psychological impairment can be used against you when they appear to conflict with current injury claims. Whether a particular file must be produced depends on the posture of the case and the objections raised.
What if my prior medical records contain errors or outdated information?
Medical record errors (incorrect diagnoses, misattributed symptoms, or outdated complaints) become part of the claims file unless they are addressed. Carriers rely on what the records say, not what they should say. Federal privacy rules give patients the right to request an amendment to their records, and clarifying letters, updated evaluations, and treating physician testimony can correct the picture. The original entry generally remains in the chart and may still be cited, but it does not have to go unanswered.
References
- Personal injury protection benefits (Fla. Stat. § 627.736)
- Comparative fault (Fla. Stat. § 768.81)
- Amendment of protected health information (45 C.F.R. § 164.526)